5 Percent Deposit Government Guarantee Loan
The 5% Deposit Scheme is a powerful government initiative designed to fast-track home ownership for eligible Australians. Traditionally,saving a 20% deposit can take years, creating a significant barrier to entry.This program dramatically lowers that hurdle, requiring only a 5% deposit to purchase your first home.
The key advantage: No Lenders Mortgage Insurance (LMI). Typically,a deposit below 20% requires you to pay LMI, a costly premium that protects the lender, not you. Under this scheme, the government guarantees a portion of your loan, allowing you to bypass this expense entirely. This can save you tens of thousands of dollars upfront, money better spent on your new home.
It's a practical solution offering real flexibility-whether you're looking at an established apartment, a new townhouse, or a brand-new build. The goal is simple: to make your path to ownership clearer, faster, and more affordable.
Eligibility Criteria for the 5% Deposit Scheme
To ensure you can benefit from this opportunity, you must meet the following clear criteria. Think of this as your pre-application checklist.
1. Who You Are
• You must be an Australian citizen or permanent resident aged 18 or over.
• You must be a first home buyer. This means you have not owned a property in Australia in the last 10 years.
2. The Property
• The property must be purchased at or below the price cap for its location (city/regional area).
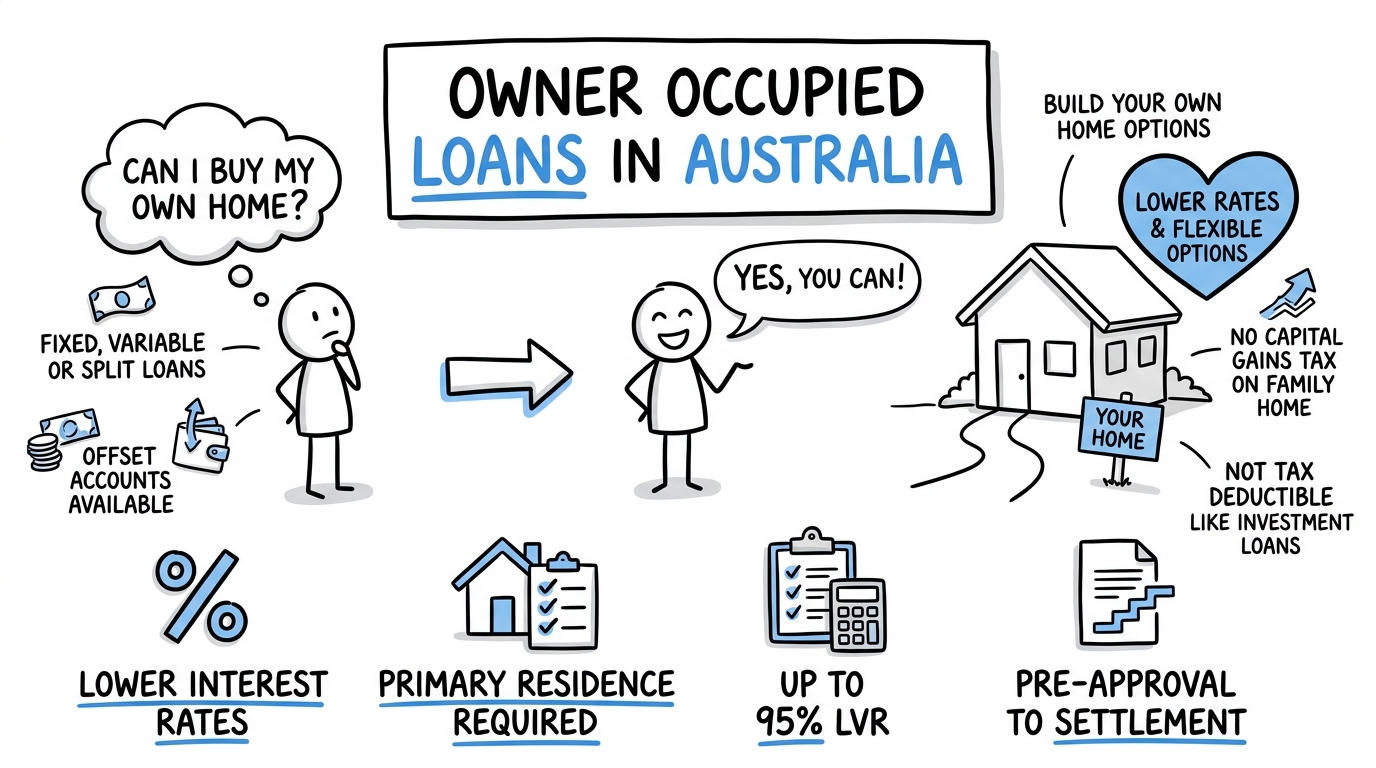
• It must be purchased to live in as your primary place of residence (owner-occupier). Investment properties are not eligible.
• Eligible properties include new or existing houses, townhouses, units or apartments.
• Vacant land with signed building contract.
3. The Finance
• You must have a minimum 5% of the purchase price for the deposit.
• Your home loan must be a principal and interest loan with a maximum term of 30 years.
• The loan must be obtained through a participating lender approved for the scheme.
4. Application Details
• You can apply as an individual or jointly with one other eligible applicant (e.g., a partner or family member).
FAQ`s
Under the scheme you are a "First Home Buyer" if you haven’t owned property in Australia in the past 10 years.
Yes. You can apply jointly with one other eligible person, such as a sibling or friend, if they also meet the scheme's criteria.
If your spouse or partner is not a first home buyer,it may affect your joint eligibility.
No, the scheme allows a maximum of two applicants.You can apply either on your own or jointly with one other eligible person (such as a partner, friend, or family member).
You cannot rent out the property till such time it is supported by the government guarantee.
Please get in touch with us and we will explain the options available to you should you want to rent out the property.
You must live in the home as your main residence till such time the property is supported by the government guarantee. Get in touch with us if your situation has changed and you cannot live in the property anymore.
Yes. Selling the property pays off the home loan,which ends the government guarantee.
Genuine savings are funds accumulated consistently over time (typically shown via bank statements), demonstrating financial discipline to lenders. If you do not have funds accumulated over time, get in touch with us and we will be able to help you qualify for genuine saving using other methods.
Yes.A gifted deposit from immediate family is usually acceptable.
Interest rates vary by lender. Most lenders would price the scheme loan “as if” the LVR is 80 percent. It's crucial to compare offers from multiple lenders.
Yes, you can refinance, to another participating lender.
No. The scheme usually requires principal and interest repayments.
The guarantee ceases while your loan's Loan-to-Value Ratio(LVR) is below or equal to 80%. Get in touch with us and we might be able to help you in getting a lower rate when the guarantee ends.
Yes.You can often combine it with benefits like the First Home Owner Grant(FHOG), provided you meet each scheme's separate eligibility rules.
The guarantee can help you avoid paying LMI with a low deposit, which may reduce upfront costs. However, LMI can sometimes be worth considering if you want a non-participating lender, different features,or don’t qualify for the guarantee (for example buying an investment property).Compare total cost over time, not just the deposit.